Property
House Deposit and LISA Tracker: A Simple First-Time Buyer Planner (UK)
Pick a target house price and deposit percentage, work out how much you need to save, then track monthly transfers and Lifetime ISA (LISA) contributions in one Google Sheet so the bonus and the timeline stay visible.
This article is general information about planning a deposit, not personalised financial advice. LISA rules and limits can change — always check the live pages on GOV.UK and MoneyHelper (or speak to a qualified adviser) before you open an account or withdraw.
Who this is for
This is for UK first-time buyers saving for a house deposit — often using a Lifetime ISA alongside a normal savings pot — who want a clear Google Sheets plan rather than scattered notes in a banking app.
You might be saving solo or with a partner. You want to see: target deposit, months left, LISA pay-ins this tax year, and whether you are on track.
This is not a mortgage application, a credit check, or tax advice. It is a planning layer.
Work out a deposit target (simple LTV maths)
Lenders talk about loan-to-value (LTV): how much of the purchase price is the mortgage vs your deposit.
A simple way to set a target:
- Choose a realistic purchase price you are aiming at (a band is fine — e.g. £220,000–£250,000)
- Choose a deposit percentage you are working towards (for example 5%, 10%, or 15% — what you can actually reach matters more than a round number)
- Deposit target ≈ price × deposit %
Example only (fictional numbers):
| Target price | £240,000 |
| Deposit aim | 10% |
| Deposit target | £24,000 |
Add a buffer for buying costs if you can (solicitor fees, surveys, moving). Those are separate from the deposit percentage a lender quotes — check current stamp duty / land tax rules for first-time buyers on GOV.UK for your nation, because reliefs change.
If you and a partner both save, decide whether the sheet tracks one shared target or two pots that add up to the same number.
What a Lifetime ISA (LISA) is for
A Lifetime ISA is a type of ISA you can use to buy your first home or save for later life.
As of the live GOV.UK guidance at the time of writing (always re-check):
- You can usually put in up to £4,000 each tax year (until you are 50), and you must make your first payment before you are 40
- The government adds a 25% bonus, up to £1,000 per year on that contribution
- The £4,000 LISA limit counts towards your overall annual ISA allowance (£20,000 for the 2026 to 2027 tax year on GOV.UK)
- For a first home, charge-free use generally requires conditions such as the property costing £450,000 or less, buying with a mortgage, and waiting at least 12 months after your first LISA payment — see withdrawing from a Lifetime ISA
- Other withdrawals can attract a 25% charge
Do not treat these figures as frozen forever. Before you max a contribution or book a completion date, open the GOV.UK page and confirm the current caps and conditions.
A LISA is only one piece of a deposit. Many buyers also use a plain savings account, Help to Buy / shared ownership schemes where relevant, gifts, or other ISAs. Your sheet should show all pots that will fund the deposit, not only the LISA.
Columns to track in a simple planner
You do not need a complex model. These fields cover most first-time buyer plans:
Targets (top of sheet)
- Target purchase price
- Deposit % and deposit £ target
- Target move / offer month (optional)
- Months remaining (or a simple countdown)
Pots
- LISA balance (and bonus noted separately if you want clarity)
- Other deposit savings balance
- Partner’s pots (if shared)
Monthly log
| Date | Pot | Amount (£) | Tax year | Notes |
|---|---|---|---|---|
| 6 Apr 2026 | LISA | 333.00 | 2026/27 | Standing order |
| 6 Apr 2026 | Easy-access | 200.00 | 2026/27 | After rent |
Useful extras
- LISA contributed so far this tax year (so you do not accidentally go over the live annual cap)
- Planned monthly total vs actual
- Gap to deposit target
- Reminder: first LISA payment date (for the 12-month rule)
Worked mini-example (fictional only):
Sam needs £24,000. They have £8,000 in a LISA (including bonuses already paid) and £3,000 in easy-access savings. Gap: £13,000. Over 24 months that is roughly £542 a month across all pots — before any future LISA bonus on new contributions. Sam’s sheet shows the monthly plan split between LISA (up to the annual cap) and other savings.
A calm monthly rhythm
- Payday: move the planned amounts into LISA and other pots the same day if you can
- Once a month: update balances on the sheet (or paste statements)
- Check the LISA tax-year total against the current GOV.UK annual limit
- Once a quarter: revisit the target price — local prices and your income may have moved
- Before you offer: confirm LISA withdrawal rules with your provider and conveyancer; funds for a first home usually go via the conveyancer, not as a casual cash withdrawal
If a month is tight, reduce the non-LISA pot first or pause extras — but note the impact on your timeline honestly on the sheet.
How the UkMoneySheets house deposit planner fits
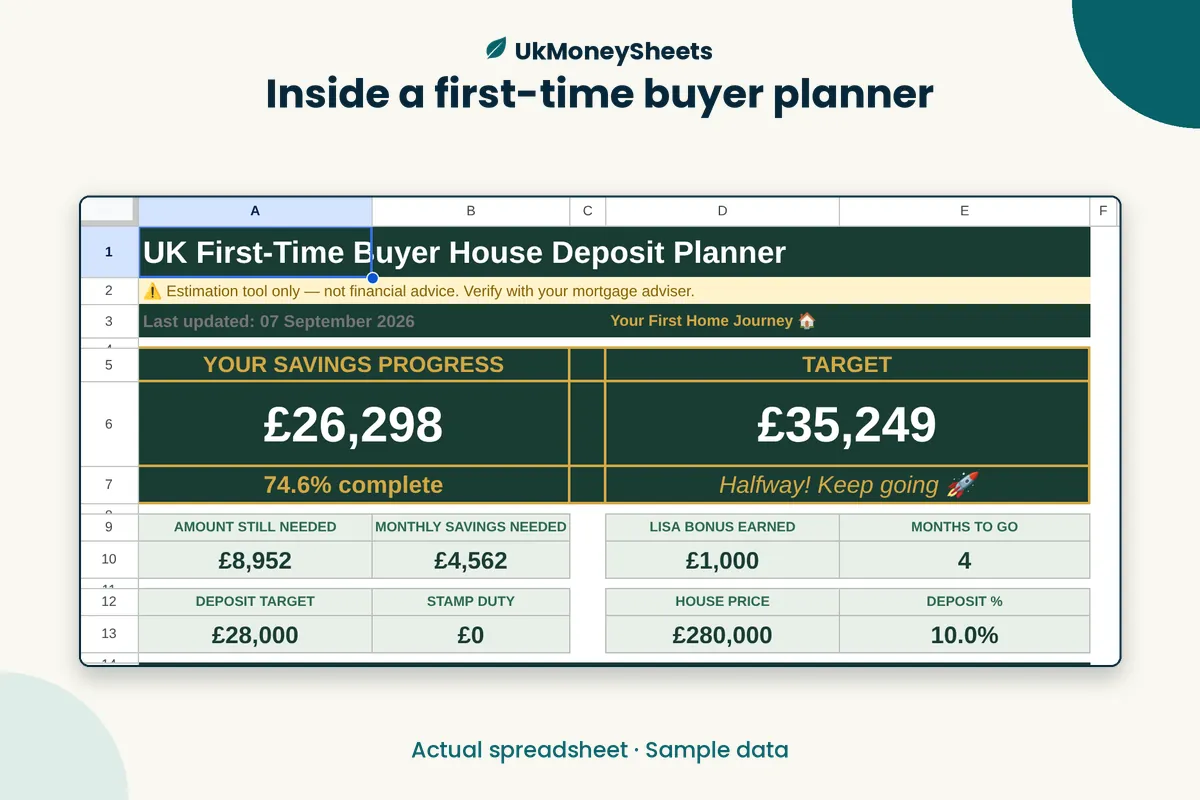
If you want a ready-made layout, UkMoneySheets sells a House Deposit Savings Planner for Google Sheets | First-Time Buyer Budget & LISA Tracker.
It is Google Sheets (not Excel). You typically receive a PDF with the Sheets link, then use File → Make a copy into your own Drive.
Related products if you are building a wider money system:
- UK Monthly Budget Spreadsheet — for the household plan that frees up the monthly transfer
- UK Net Worth Tracker
- UK Money Toolkit bundle
A template organises the numbers. It does not guarantee a mortgage offer, a bonus payment, or that a property will qualify under LISA rules.
FAQ
How much deposit do I need?
It depends on the price and the LTV your lender will accept. Many first-time buyers aim for at least 5–10%, but products vary. Work backwards from a price band you can realistically buy, then confirm with a mortgage broker or lender — not with a spreadsheet alone.
How much can I put in a LISA?
Check GOV.UK Lifetime ISA. At the time of writing the annual contribution limit shown there is £4,000, with a 25% bonus up to £1,000 a year, counting towards the wider ISA allowance. Re-check before you pay in.
Can a spreadsheet replace MoneyHelper or a broker?
No. Use MoneyHelper’s LISA guide for impartial explanations, and a regulated adviser or broker for product and mortgage decisions. The sheet is your tracker.
Is this financial advice?
No. This article and any UkMoneySheets template are for organisation and education only.
Soft next step
Write your target price and deposit % on one line. Add every pot that will fund it. Schedule the monthly transfers.
If you want a UK-ready Google Sheet built for first-time buyer deposit and LISA tracking, get the House Deposit Savings Planner from UkMoneySheets on Etsy, make your own copy, and keep the monthly update.
Then confirm every LISA figure on GOV.UK before you rely on it for a completion date.
Disclaimer
Not tax or financial advice. Rules, allowances and product names change — GOV.UK is the source of truth. Confirm the live Etsy listing before purchase. UkMoneySheets templates are Google Sheets only (never Excel), delivered as a PDF with a copy link, prices in GBP.
Browse UkMoneySheets on Etsy